S&V Weekly Newsletter Vol. 12 No. 20, May 18 2026
Download PDF
To prevent our emails from being false flagged as spam and to ensure you receive our publications, please consider white listing our email address - tony@svmag.co.za
Please note: Click on any ad to go to the advertiser's website
Wage negotiations
No settlement after 2 rounds for General Goods & Handbags, Footwear sectors
Ilhaam Ryneveld, General Secretary / Principal Officer, National Bargaining Council of the Leather Industry of SA
Durban, KZN, SA – Please be advised of the following developments in the current wage negotiations:
•General Goods and Handbags Sector: The second round of negotiations has been concluded. No agreement has been reached at this stage, as the union has requested additional time to consult with its members. A formal response is expected by Friday, 22 May 2026.
•Footwear Sector: The second round of negotiations took place on 11 and 12 May 2026. No agreement was reached, and a date for the third round has not yet been scheduled.
•Tanning Sector: The second round of negotiations is scheduled for 28 and 29 May 2026.
Manufacturing
Update on various initiatives
A joint statement from the DTIC, SAFLIA and SAFLEC
Industry Update: Collective Efforts Strengthening the Safety Footwear Sector
The South African safety footwear industry continues to build momentum through coordinated action by the Department of Trade, Industry and Competition (dtic), SAFLIA, and SAFLEC. These engagements highlight a unified commitment to advancing the sector, tackling compliance challenges, and ensuring that stakeholders speak with one voice while respecting their individual mandates.
Key Engagements and Leadership
•SARS Industry Meeting
Lead: Dtic and SAFLIA, SARS has agreed to meet directly with the industry to address compliance concerns and strengthen enforcement. Engagements facilitated by Director Dimakatso Moji, this initiative will be led by the dtic, SAFLIA, with SAFLEC to particularly Customs, to address challenges relating to illegal and under-declared imports, tariff evasion, counterfeit goods, customs enforcement, import monitoring and the protection of local manufacturing through localisation and import substitution measures. These engagements are aimed at ensuring fair trade conditions, strengthening compliance with compulsory specifications, supporting industrialisation and protecting jobs within the sector. To note: A formal complaint has been lodged with SARS regarding mis declared canvas footwear sold as safety shoes. The matter will be escalated to the Inter-Agency Working Group for coordinated enforcement.
•Electra Mining Exhibition
Lead: SAFLEC, supported by dtic SAFLEC is preparing to secure exhibition space at this flagship event, ensuring strong representation for the safety footwear sector.
•Mining Indaba
Lead: SAFLEC, supported by dtic SAFLEC has approached dtic for assistance to enable manufacturers to attend this premier international event. Exhibition costs remain prohibitive, but discussions with dtic are ongoing.
•Trade Mission Guidelines
Lead: dtic, with industry input from SAFLEC -A request has been made to dtic to include larger companies in the guidelines for trade missions. While this is a long process with many hurdles, conversations are now on the table, signalling progress toward more inclusive participation.
•Safety Footwear Meeting
Lead: dtic and SAFLIA, supported by SAFLEC dtic has requested a meeting with manufacturers at SAFLIA offices to engage on industrial development, localisation, regulatory compliance, competitiveness and import substitution opportunities within the sector. These engagements are aimed at strengthening local manufacturing capacity, protecting and creating jobs, improving participation of locally produced safety footwear in public and private procurement, and addressing challenges such as illegal imports, unfair competition and non-compliant products entering the South African market. The dtic also engages the industry to align stakeholders on implementation of the Retail-Clothing, Textile, Footwear and Leather (R-CTFL) Masterplan, explore beneficiation opportunities such as the local production of steel toe caps and other inputs, support transformation and SMME participation, and ensure that compulsory specifications and quality standards are enforced to protect end users and promote confidence in locally manufactured safety footwear. The dtic has had meeting with NRCS and requested NRCS to attend the meeting scheduled meeting on Friday 22 May 2026.. SAFLEC will support on related matters that aid exports. If you are a Safety Footwear manufacturer and have not received correspondence, please contact SAFLIA.
ITAC Standards Review
Lead: dtic and SAFLIA, SAFLEC (export related issues) -ITAC has requested industry input on safety footwear standards (SANS 20345). The review may consider mechanisms such as Pre-Export Verification of Conformity (PVoC) to ensure uniform enforcement.
Collective Mandate and Unified Voice
Through these initiatives, dtic, SAFLIA, and SAFLEC are working together to:
•Safeguard industry integrity and competitiveness.
•Address compliance challenges with stronger enforcement.
•Create local manufacturing opportunities to drive industrialisation.
•Ensure sector representation at key platforms like Mining Indaba and Electra Mining and grow exports
•Broaden trade mission access to include larger companies.
Speaking with one voice is proving essential to securing the future of the industry. Incremental successes are already visible, and with continued alignment, measurable progress will benefit all stakeholders.

Components
Trends in PVC
The Southern African Vinyls Association will hold an online AGM and presentation on 21 May at 11.00. Guest speaker will be Jonathan Davies, head of global PVC sales & sourcing at Vinmar International, who will speak on key market trends and developments, oil price movements and implications, potential supply constraints, and pricing outlooks. Visit www.sava.co.za for more information.
Automotive
Automotive exports reached R291 billion in 2025
naamsa | The Automotive Business Council
Pretoria, Gauteng, SA (Friday 15 May 2026) – The annual Automotive Trade Manual 2026 publication as the official source of all key automotive data in South Africa. This is the 20th annual publication since 2007, providing a comprehensive overview of the export and import performance of the South African automotive industry under the Automotive Production Development Programme (APDP) and APDP Phase 2 (APDP2)
Amidst adversity, the domestic new vehicle market and vehicle exports have shown remarkable growth in 2025. Once again, automotive exports have remained a pillar of South Africa’s automotive industry, as the export value of vehicles and automotive components increased from R268,8 billion in 2024 to a record R291,0 billion in 2025, comprising a significant 15,6% of total South African exports. Vehicle exports increased to a record 414 271 units in 2025, up from the 391 128 units exported in 2024. The vehicle export value increased from R205,4 billion in 2024 to a record R229,8 billion in 2025, however, automotive component exports reflected a decrease of R2,2 billion from R63,4 billion in 2024 to R61,2 billion in 2025. The domestic automotive industry exported to 154 countries in 2025, slightly down from the 155 destinations in 2024; with the export value more than doubling in the case of 29 of these countries from 2024 to 2025. South African automotive trade under the APDP2, amounting to a substantial R546,7 billion in 2025, comprised 15,3% of South Africa’s total trade GDP.
Manufacturing offers a proven path to sustainable growth and transformation of the whole economy. As the engine of industrial growth and largest manufacturing sector in the country, a substantial 23,8% of value addition within the domestic manufacturing output was derived from vehicle and automotive component manufacturing in 2025, while the broader automotive industry’s contribution to the GDP comprised 5,2% (3,3% manufacturing and 1,9% retail).
Driven by lower interest rates, record low vehicle price inflation and a broader model and price choice, new vehicle sales increased by a sound 15,7% to 597 338 units in 2025, compared to the 516 103 units sold in 2024. The most dramatic shift in 2025 has been the meteoric rise of imported Chinese brands in the domestic light vehicle market, offering modern technology, competitive pricing and long warranties which have assisted them to move into the mainstream. Affordability and choice continue to redefine the domestic landscape in creating one of the most competitive trading environments. Compared to global standards, in 2025 there were no less than 56 passenger car brands and 1 995 model derivatives, the greatest selection of market-size ratio found globally. Similarly, in the light commercial vehicle segment, for the same period, there were 30 brands with 665 model derivatives to choose from. New energy vehicle (NEV) sales reflected an increase of 7,1% from 15 611 units in 2024 to 16 716 units in 2025, following the impressive year-on-year increase of 100,6% in 2024. NEV sales share, by 30 brands, as a percentage of total new vehicle sales, decreased to 2,8% in 2025, down from 3,0% in 2024.
As an export-oriented industry, the South African automotive industry’s export performance continues to highlight both market concentration as well as the expanding global reach. The long-standing free trade agreements with the EU and the UK ensured record exports to the region to the value of R182,8 billion, or 62,8%, of the total automotive export value of R291,0 billion in 2025. Light vehicles remained the dominant export category, with 80,3%, or four out of every five vehicles exported in 2025 destined for the region. Africa comprised the domestic automotive industry’s second-largest export region, accounting for R49,5 billion, or 17,0% of the total automotive exports of R291,0 billion with 85,1% of the export value destined for SADC, which is a free trade area. With the outstanding rules of origin for automotives now being adopted since February 2026 under the African Continental Free Trade Area (AfCFTA), it would open up further market access opportunities for the domestic automotive industry to the rest of Africa.
A total of 414 271 left- and right-hand drive vehicles were exported to 109 countries around the world in 2025. In 2025, Germany remained the top export destination since 2023, followed by the UK, France, Belgium and Italy. For the sixth consecutive year, the Volkswagen Polo was once again the most exported vehicle model in South Africa in 2025. A significant 70,5% of light vehicle production was exported in 2025, enabling the domestic OEMs to reach a consumer base beyond the South African market.
In 2025, automotive component exports decreased by R2,2 billion, or 3,5%, to R61,2 billion, from R63,4 billion in 2024, mainly due to the ongoing decrease in catalytic converter exports. However, catalytic converters remained the top automotive component exported from South Africa, comprising 26,0% of total automotive component exports, followed by engine parts, tyres and transmission shafts and cranks. The global transition to electric vehicles is creating new potential demand for domestic component suppliers able to adapt. Research has indicated that South Africa is well positioned to localise high-value NEV components, including fuel cells, thermal management systems, e-axles, high-voltage battery mineral beneficiation, and battery assembly.
New light vehicles (passenger cars and light commercial vehicles) imported into South Africa originated from 25 countries. Imports of light vehicles increased by 87 112 units, or 28,6%, from 304 175 units in 2024 to 391 287 units in 2025. Light vehicle imports as a percentage of total light vehicle sales increased from 62,7% in 2024 to 69,1% in 2025. Passenger car imports accounted for 82,8% of total passenger car sales of 422 463 units in 2025. The top country of origin, in volume terms was India, with 219 796 vehicles, accounting for 56,2% of the total light vehicles imported, while China, with 91 326 units in second position, gained further popularity, increasing its share to 23,3%, up from 17,1% in 2024. Several global brands have established India as a production hub for small car plants, and most of the vehicles imported from India fell in the small car and entry-level segments. India specialises in small, entry-level vehicles, which have grown in popularity in the domestic market. Volkswagen’s Polo Vivo was the only vehicle in these segments that was manufactured in South Africa in 2025. There were 15 different brands from China operating in the domestic new vehicle market in 2025, up from eight in 2024, with more to follow in 2026.
The South African automotive industry remains heavily reliant on imported components, particularly for assembly lines and aftermarket parts supply. Imports of original equipment (OE) components by the seven domestic OEMs increased by R3,6 billion, or 2,4%, to R151,0 billion in 2025, up from R147,4 billion in 2024, in line with higher vehicle production volumes supporting higher vehicle exports. In 2025, the import of replacement parts increased by R2,7 billion, or 2,6%, to R107,5 billion, up from R104,8 billion in 2024, in line with the expansion of the national vehicle parc and higher vehicle imports. In the South African context, aftermarket parts are supplied by domestic component suppliers focusing mainly on the domestic models manufactured in the country, while foreign aftermarket parts are generally linked to imported models.
In 2025, South Africa’s automotive industry maintained a positive trade balance, despite rising vehicle imports as the export-driven industry helped sustain a trade surplus in automotive products, supporting economic growth and job creation amid global supply chain challenges and shifting market dynamics. Vehicle imports increased in 2025 due to the rising consumer demand for affordable passenger cars, along with an increase in automotive components not produced domestically. The trade balance under the APDP2 measurement reflected a trade surplus of R35,3 billion in 2025, compared to R42,8 billion in 2024.
Global vehicle production in 2025 increased by 3,9% to reach 96,4 million vehicles, up from the 92,7 million units produced in 2024. China’s automotive industry continued to set new records in 2025, with vehicle production reaching 34,5 million units, up 10,4% year-on-year, marking the 17th consecutive year China has led global vehicle output, followed by the US with 10,2 million units, Japan with 8,4 million units and India with 6,5 million units. Demand for vehicles continued to rise despite economic shifts, marking the first year to surpass the 2019 pre-pandemic level as global new vehicle sales in 2025 increased by 4,7% to 99,8 million units, up from the 95,3 million units in 2024. China sold 34,4 million vehicles in 2025, up 9,4% from the 31,4 million units in 2024 and remained by far the largest single-country new vehicle market in the world, selling almost as many vehicles as the European and US markets combined. The year 2025 turned out to be another record year for EVs, with worldwide sales surging by 21% to 20,7 million units, up from 17,1 million units in 2024, with China producing 71% of EVs sold globally.
In 2025, 17 countries exceeded the one million vehicle production mark, which is regarded as the international benchmark. South Africa forms part of the group of global second-tier countries producing below one million vehicles per annum. The country’s vehicle production increased by 2,9%, from 600 473 units in 2024 to 618 077 units in 2025, slightly below the year-on-year increase in global vehicle production of 3,9% in 2025. South Africa’s global vehicle production market share thus decreased from 0,65% in 2024 to 0,64% in 2025, while its global vehicle production ranking remained at 21st. In terms of global LCV production, the country was ranked 15th, with a market share of 1,2%. South Africa remained the dominant market on the African continent and accounted for 50,3% of the total African vehicle production of 1,23 million vehicles and 46,5% of sales of 1,29 million in 2025.
South Africa’s automotive industry, as the cornerstone of the national manufacturing sector, is entering new territory as it is under pressure to transition towards a more sustainable and ever-increasingly globally competitive future. Growth prospects for the South African automotive industry will depend on a combination of effective and progressive policy support, strong export markets, increased localisation, technological transition to NEVs, improved logistics and infrastructure, and dynamic adaptability to a highly unpredictable global environment.
In case you missed it!
The May issue of S&V African Leather Magazine
S&V African Leather Magazine Vol20 No5 May 2026
IN THIS ISSUE:
03 Sam Setter’s ‘Pills’
- A new quip from Sam Setter in each issue.
05 Upfront
- FMD: Government upbeat, but little comment from industry. - Southern African Regional Leather Network ‘aims for business and regulatory advocacy for the leather value chain across SADC’.
07 Leather, Its Image & Its Place In The World
- Africa needs to mobilise its natural livestock resource to reinvigorate the regional leather value chain, writes the Sustainable Leather Foundation’s Deborah Taylor.
11 An Eclectic View
- Money from waste: Europe has borne the difficulties and the costs of converting to a bioeconomy – the lessons are there, free, for African businesses to learn and profit from, writes correspondent H. Procter.
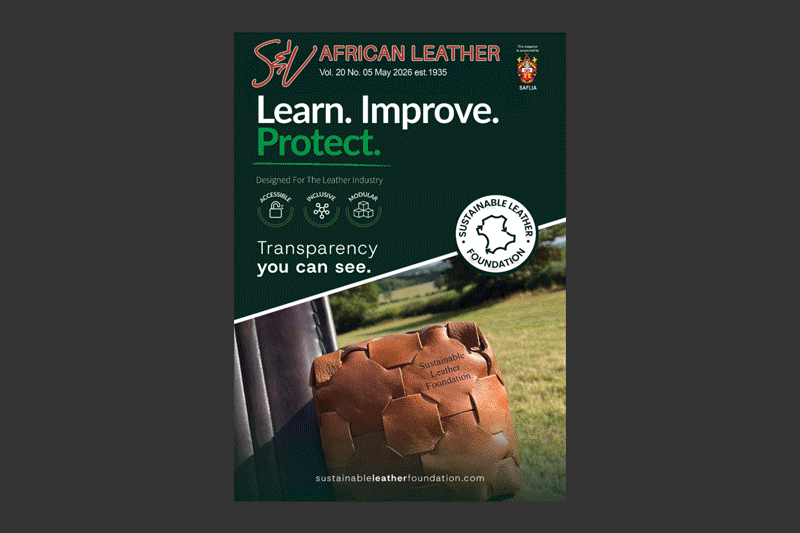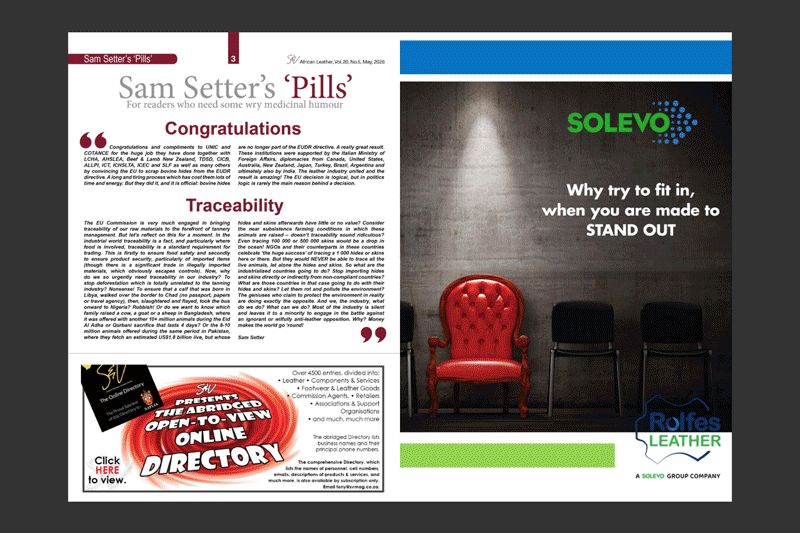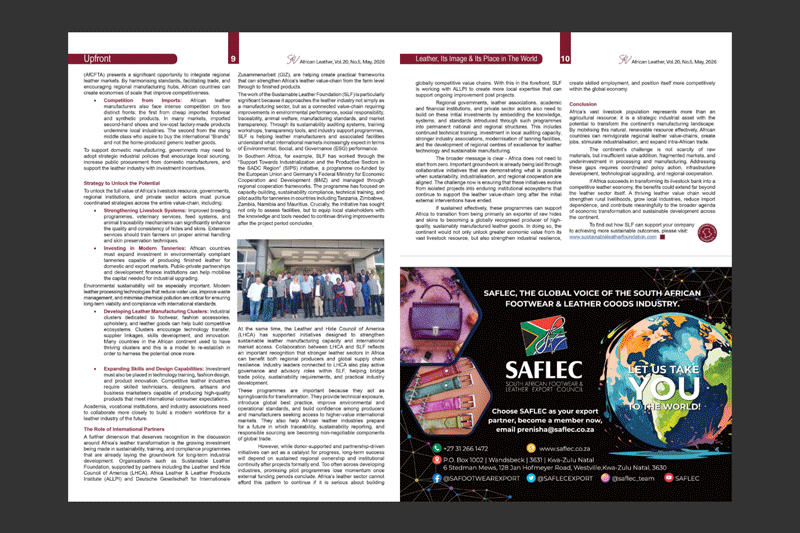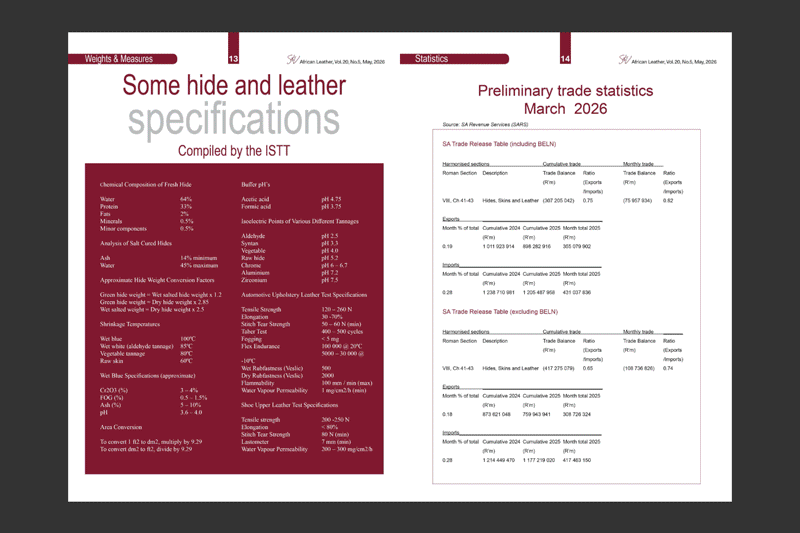
13 Weights & Measures
- Compiled by the ISTT.
14 Statistics
- Preliminary South African trade statistics for February 2026.
Advertisers in this Issue
Authenticae (02), International School of Tanning Technology (ISTT) (07), Rolfes Leather Division (04), S&V Calendar (01), S&V Directory (03), Southern African Footwear & Leather Export Council (SAFLEC) (10), Sustainable Leather Foundation (OFC).
They Said It
“Do the best you can until you know better. Then when you know better, do better.” - Maya Angelou, Southern New Hampshire University. This is what AI suggested as the best quote on Saturday.
Got anything you'd like to share?
Do you have any suggestions, comments or experiences about the industry that you'd like to share with the industry? - tony@svmag.co.za
New subscribers last week
Crystal, Health and safety representative, Labour law distributors, Boksburg, South Africa
Eliot Biriyadi, Business Development Manager, Lupane State University, Lupane, South Africa
Mateboho, Rose leather works, Maseru, Lesotho
Dr Charles Tsorayi, Consultant, Unique Empowering Company (Pvt) Ltd, Harare, Zimbabwe
Kevin Zinyama, Product Dev Mgr, Bata Shoe Co, Zimbabwe
Annie Chifulemba, CEO, Joan Investments, Blantyre, Malawi
Zorah Kaukau, Marketing, Zorye Harvest Company, Harare, Zimbabwe
Birthdays this week
18/05/1955: George Newton, Footwear Industry Training (Pty) Ltd, Cape Town, W. Cape, SA.
18/05/1969: Andrew Lofthouse, emigrated, formerly Leather Systems, Port Elizabeth, E. Cape, SA.
18/05/1974: Rudolph de L. Volschenk, Leo D’ Mar, George, W. Cape, SA.
19/05/1970: Chalkie Harrower, C&B Harrower Agencies, Johannesburg, Gauteng, SA.
20/05/1934: Diana Beckley, retired, formerly agent, Durban, KZN, SA.
20/05/1951: Sam Ferreira, Samfer Equipment Technologies, Cape Town, W. Cape, SA.
21/05/1949: Donald Blanshard, Foot Fashion, Johannesburg, Gauteng, SA.
21/05/1949: Norman Norris, retired, formerly Urban Zone, Randburg, Gauteng, SA, now South Coast, KZN.
21/05/1949: Diana Teplitsky-Keffler, Teplov Shoes & Dancewear, Somerset West, W. Cape, SA.
21/05/1976: Sandeep Chunilal, Speri, Johannesburg, Gauteng, SA.
21/05/1987: Matthew Dunning, Trumpler Leather Chemicals, Worms, Germany, formerly NTE, Pietermaritzburg, KZN, SA.
22/05/1958: Craig Wells, Sidison Footwear Cape Town, W. Cape, SA.
22/05/1972: Cindy Dunbar, Naked Feet, Durban, KZN, SA.
22/05/????: Dr Willem Burger, SAOBC Ostrich Research, Oudtshoorn, W. Cape, SA.
22/05/1973: Farai Musungwa, Safety-Quip Botswana, Francistown, Botswana.
23/05/1950: Dean Padayachee, retired, formerly Daylan Footwear (closed), Durban, KZN, SA.
23/05/1952: Martin Cohen, L. Cohen Outfitters, Cape Town, W. Cape, SA.
23/05/1965: Craig Harper, left the industry, formerly Wayne Rubber, Palmer Rubber and Egoli Gumboots (all closed), Amanzimtoti, KZN, SA.
24/05/1965: Wayne Stanford, emigrated, formerly agent, East London, E. Cape, SA.
24/05/1970: Carla Maritz, Mott! Shu’s, Pretoria, Gauteng, SA.
24/05/1972: Terry Fowler, BBF Safety Group, Cape Town, W. Cape, SA.

In memoriam this week
19/05/2009: Robbie Trench (b. 28/03/1945), Panama Shoes, RPM Footwear (both closed), Durban, KZN, SA.
19/05/2022: Tony O'Hagan (b. 13/05/1941), retired, formerly MD, Adidas SA, Cape Town, W. Cape, SA.
21/05/2019: Theo Heffer (b. 06/12/1934), Association of SA Manufacturers of Luggage, Handbags & General Goods, Johannesburg, Gauteng, SA.
23/05/2012: Chris van der Merwe, Oasis Tanning, Krugersdorp, Gauteng, SA.
23/05/2020: Cyril Saxe (b. 02/10/1936), Lonshoe Holdings, Cape Town, W. Cape, SA.
24/05/2013: Casper Louw (b. 11/04/1944), Busy Bag (closed), Stanger, KZN, SA.
Have you let us know about your birthday, or the birthdays of your colleagues? Our readers love this section, so please become part of it. This also applies to the In Memoriam section. Help us remember former colleagues.
Directory entries updated last week
Mirzapore and Supergo Distributors (Pty) Ltd, Johannesburg, Gauteng, SA.
Fairs & events updated last week – see calendar for details
2027/02/21-23: Micam Milano and Mipel
2027/09/12-14: Micam Milano
 

Exchange rates
Note: For previous rates, see HERE
1. SA Rand (ZAR)/Lesotho Loti (LSL)/Namibian Dollar (NAD)/Swazi Lilangeni (SZL)
Source: http://www.x-rates.com/calculator/
| |
Euro € |
GBP £ |
US $ |
CNY ¥ |
| 06/12/2025 |
R19.70 |
R22.57 |
R16.92 |
R 2.39 |
| 13/12/2025 |
R19.76 |
R22.55 |
R16.84 |
R 2.38 |
| 20/12/2025 |
R19.64 |
R22.44 |
R16.77 |
R 2.38 |
| 29/12/2025 |
R19.66 |
R22.52 |
R16.70 |
R 2.38 |
| 03/01/2026 |
R19.33 |
R22.18 |
R16.48 |
R 2.35 |
| 10/01/2026 |
R19.19 |
R22.10 |
R16.49 |
R 2.35 |
| 17/01/2026 |
R19.02 |
R21.95 |
R16.40 |
R 2.35 |
| 24/01/2026 |
R19.06 |
R22.01 |
R16.12 |
R 2.31 |
| 31/01/2026 |
R19.15 |
R22.12 |
R16.16 |
R 2.32 |
| 07/02/2026 |
R18.93 |
R21.81 |
R16.02 |
R 2.31 |
| 16/02/2026 |
R18.90 |
R21.72 |
R15.92 |
R 2.30 |
| 21/02/2026 |
R18.88 |
R21.60 |
R16.03 |
R 2.32 |
| 28/02/2026 |
R18.77 |
R21.43 |
R15.89 |
R 2.31 |
| 07/03/2026 |
R19.24 |
R22.20 |
R16.55 |
R 2.39 |
| 14/03/2026 |
R19.33 |
R22.39 |
R16.93 |
R 2.45 |
| 21/03/2026 |
R19.70 |
R22.67 |
R16.99 |
R 2.46 |
| 28/03/2026 |
R19.68 |
R22.80 |
R17.07 |
R 2.47 |
| 06/04/2026 |
R19.47 |
R22.31 |
R16.87 |
R 2.45 |
| 11/04/2026 |
R19.26 |
R22.11 |
R16.42 |
R 2.40 |
| 18/04/2026 |
R19.24 |
R22.09 |
R16.41 |
R 2.40 |
| 25/04/2026 |
R19.37 |
R22.36 |
R16.52 |
R 2.41 |
| 02/05/2026 |
R19.51 |
R22.59 |
R16.64 |
R 2.43 |
| 09/05/2026 |
R19.29 |
R22.31 |
R16.37 |
R 2.40 |
| 16/05/2026 |
R19.39 |
R22.23 |
R16.68 |
R 2.44 |
2. Botswana Pula
Source: http://www.x-rates.com/calculator/
| |
Euro € |
GBP £ |
US $ |
CNY ¥ |
| 06/12/2025 |
15.43 |
17.67 |
13.25 |
1.87 |
| 13/12/2025 |
15.54 |
17.74 |
13.25 |
1.87 |
| 20/12/2025 |
16.46 |
18.80 |
14.05 |
1.99 |
| 29/12/2025 |
15.66 |
17.93 |
13.29 |
1.89 |
| 03/01/2026 |
16.40 |
18.81 |
13.98 |
1.99 |
| 10/01/2026 |
15.41 |
17.74 |
13.24 |
1.89 |
| 17/01/2026 |
15.49 |
17.88 |
13.36 |
1.91 |
| 24/01/2026 |
15.75 |
18.18 |
13.32 |
1.91 |
| 31/01/2026 |
15.43 |
17.82 |
13.02 |
1.87 |
| 07/02/2026 |
15.59 |
17.96 |
13.19 |
1.90 |
| 16/02/2026 |
15.55 |
17.88 |
13.11 |
1.89 |
| 21/02/2026 |
15.60 |
17.84 |
13.24 |
1.91 |
| 28/02/2026 |
15.54 |
17.73 |
13.15 |
1.91 |
| 07/03/2026 |
15.50 |
17.89 |
13.34 |
1.93 |
| 14/03/2026 |
15.56 |
18.02 |
13.63 |
1.97 |
| 21/03/2026 |
15.80 |
18.18 |
13.63 |
1.97 |
| 28/03/2026 |
15.89 |
18.41 |
13.78 |
1.99 |
| 06/04/2026 |
15.80 |
18.10 |
13.68 |
1.98 |
| 11/04/2026 |
15.76 |
18.10 |
13.44 |
1.97 |
| 18/04/2026 |
15.77 |
18.10 |
13.44 |
1.97 |
| 25/04/2026 |
15.77 |
18.21 |
13.46 |
1.96 |
| 02/05/2026 |
15.83 |
18.34 |
13.50 |
1.97 |
| 09/05/2026 |
15.85 |
18.34 |
13.45 |
1.97 |
| 16/05/2026 |
16.44 |
18.85 |
14.15 |
2.07 |
3. Malawian Kwacha (MWK) (buying)
Source: https://www.rbm.mw/
| |
Euro € |
GBP £ |
US $ |
ZAR |
| 06/12/2025 |
2061.93 |
2360.63 |
1717.02 |
104.35 |
| 13/12/2025 |
2075.72 |
2368.42 |
1717.02 |
104.97 |
| 20/12/2025 |
2072.54 |
2365.59 |
1717.02 |
105.59 |
| 29/12/2025 |
2080.15 |
2385.39 |
1717.02 |
106.07 |
| 03/01/2026 |
2076.96 |
2381.50 |
1717.02 |
106.95 |
| 10/01/2026 |
2059.98 |
2373.72 |
1717.02 |
106.93 |
| 17/01/2026 |
2053.09 |
2365.94 |
1717.02 |
108.10 |
| 24/01/2026 |
Not available on Saturday |
| 31/01/2026 |
2109.86 |
2433.50 |
1717.02 |
111.06 |
| 07/02/2026 |
2086.69 |
2400.43 |
1717.02 |
109.25 |
| 16/02/2026 |
2095.18 |
2403.26 |
1717.02 |
110.17 |
| 21/02/2026 |
2079.26 |
2380.09 |
1717.02 |
109.55 |
| 28/02/2026 |
2087.57 |
2382.39 |
1717.02 |
111.26 |
| 07/03/2026 |
2053.09 |
2363.29 |
1717.02 |
106.72 |
| 14/03/2026 |
2029.39 |
2351.44 |
1717.02 |
104.73 |
| 21/03/2026 |
2044.95 |
2370.89 |
1717.02 |
105.26 |
| 28/03/2026 |
2040.18 |
2358.51 |
1717.02 |
103.57 |
| 06/04/2026 |
2038.76 |
2336.05 |
1717.02 |
104.11 |
| 11/04/2026 |
2066.88 |
2372.66 |
1717.02 |
109.75 |
| 18/04/2026 |
2082.97 |
2388.93 |
1717.02 |
107.70 |
| 25/04/2026 |
2065.64 |
2381.15 |
1717.02 |
106.19 |
| 02/05/2026 |
2065.47 |
2384.69 |
1717.02 |
105.12 |
| 09/05/2026 |
2076.25 |
2401.66 |
1717.02 |
107.72 |
| 16/05/2026 |
2058.22 |
2360.63 |
1717.02 |
106.41 |
4. Zambian Kwacha (ZMW) (buying)
Source: https://www.boz.zm/
| |
Euro € |
GBP £ |
US $ |
ZAR |
| 06/12/2025 |
26.84 |
30.76 |
23.05 |
1.36 |
| 13/12/2025 |
26.94 |
30.73 |
22.97 |
1.36 |
| 20/12/2025 |
26.48 |
30.23 |
22.62 |
1.34 |
| 29/12/2025 |
26.51 |
30.35 |
22.48 |
1.34 |
| 03/01/2026 |
25.84 |
29.63 |
22.04 |
1.33 |
| 10/01/2026 |
22.69 |
26.14 |
19.49 |
1.17 |
| 17/01/2026 |
23.21 |
26.76 |
19.98 |
1.21 |
| 24/01/2026 |
23.05 |
26.56 |
19.63 |
1.21 |
| 31/01/2026 |
23.49 |
27.10 |
19.72 |
1.23 |
| 07/02/2026 |
21.98 |
25.33 |
18.64 |
1.15 |
| 16/02/2026 |
21.71 |
24.91 |
18.30 |
1.14 |
| 21/02/2026 |
22.91 |
25.44 |
18.88 |
1.17 |
| 28/02/2026 |
22.16 |
25.29 |
18.77 |
1.17 |
| 07/03/2026 |
22.28 |
25.73 |
19.29 |
1.14 |
| 14/03/2026 |
22.26 |
25.74 |
19.40 |
1.15 |
| 21/03/2026 |
22.52 |
26.04 |
19.52 |
1.14 |
| 28/03/2026 |
21.81 |
25.17 |
18.91 |
1.10 |
| 06/04/2026 |
22.20 |
25.45 |
19.26 |
1.13 |
| 11/04/2026 |
22.50 |
25.84 |
19.19 |
1.17 |
| 18/04/2026 |
22.54 |
25.85 |
19.04 |
1.17 |
| 25/04/2026 |
22.01 |
25.37 |
18.80 |
1.13 |
| 02/05/2026 |
21.93 |
25.34 |
18.76 |
1.12 |
| 09/05/2026 |
22.38 |
25.89 |
19.00 |
1.16 |
| 16/05/2026 |
21.91 |
25.17 |
18.84 |
1.13 |
5. Zimbabwe Gold (ZiG)
Source: Source: https://www.rbz.co.zw/
| |
Euro € |
GBP £ |
US$ |
ZAR |
| 06/12/2025 |
ZIG 30.46 |
ZIG 34.87 |
ZIG 26.13 |
ZIG 0.64 |
| 13/12/2025 |
ZIG 30.63 |
ZIG 34.96 |
ZIG 26.10 |
ZIG 0.64 |
| 20/12/2025 |
ZIG 30.58 |
ZIG 34.90 |
ZIG 26.09 |
ZIG 0.64 |
| 29/12/2025 |
ZIG 30.58 |
ZIG 35.09 |
ZIG 26.01 |
ZIG 0.64 |
| 03/01/2026 |
Not available on Saturday |
| 10/01/2026 |
Not available on Saturday |
| 17/01/2026 |
Not available on Saturday |
| 24/01/2026 |
ZIG 30.08 |
ZIG 34.55 |
ZIG 25.60 |
ZIG 0.62 |
| 31/01/2026 |
ZIG 30.48 |
ZIG 35.17 |
ZIG 25.58 |
ZIG 0.61 |
| 07/02/2026 |
ZIG 30.19 |
ZIG 34.71 |
ZIG 25.59 |
ZIG 0.63 |
| 16/02/2026 |
ZIG 30.32 |
ZIG 34.86 |
ZIG 25.56 |
ZIG 0.62 |
| 21/02/2026 |
ZIG 30.01 |
ZIG 34.32 |
ZIG 25.53 |
ZIG 0.63 |
| 28/02/2026 |
ZIG 30.44 |
ZIG 34.77 |
ZIG 25.77 |
ZIG 0.61 |
| 07/03/2026 |
ZIG 29.90 |
ZIG 34.35 |
ZIG 25.75 |
ZIG 0.63 |
| 14/03/2026 |
ZIG 29.27 |
ZIG 33.93 |
ZIG 25.45 |
ZIG 0.65 |
| 21/03/2026 |
ZIG 29.25 |
ZIG 33.93 |
ZIG 25.31 |
ZIG 0.66 |
| 28/03/2026 |
ZIG 29.28 |
ZIG 33.84 |
ZIG 25.37 |
ZIG 0.67 |
| 06/04/2026 |
ZIG 29.28 |
ZIG 33.84 |
ZIG 25.37 |
ZIG 0.67 |
| 11/04/2026 |
ZIG 29.41 |
ZIG 33.76 |
ZIG 25.16 |
ZIG 0.65 |
| 18/04/2026 |
Not available on Saturday |
| 25/04/2026 |
ZIG 29.45 |
ZIG 33.95 |
ZIG 25.21 |
ZIG 0.66 |
| 02/05/2026 |
ZIG 29.55 |
ZIG 34.12 |
ZIG 25.34 |
ZIG 0.66 |
| 09/05/2026 |
ZIG 29.97 |
ZIG 34.66 |
ZIG 25.76 |
ZIG 0.64 |
| 16/05/2026 |
ZIG 30.05 |
ZIG 34.47 |
ZIG 25.81 |
ZIG 0.64 |
Note: For previous rates, see HERE
ABSA Agri Trends: Hides & skins prices
Johannesburg, Gauteng, SA (15 May 2026) - The current average hide price decreased by 1.46% to R2,223/kg from R2.256/kg, in the previous week. The current price is 1.82% lower than the average price a month ago and was 10.5% lower than the average price a year ago. The range of prices reported was as follows: Minimum price: R2.00 Maximum price: R2.29. Please note: Our methodology weighs the prices we collect according to the number of hides they sell in a month. This is done to make it more representative of the prevailing market price. NB* Hide prices are determined by the average of the RMAA (Red Meat Abattoir Association) and independent companies. - Marlene Louw, senior agricultural economist, Nkhensani Mashimbyi, agricultural economist, and Zama Sangweni, agricultural economist, ABSA group.
Note: For previous prices, see HERE
Have a look at these links
We invite businesses to send us links to websites, Facebook pages and the like which they feel would be of interest to others. The links below are from our database:
J.L. Maister (Cape), Cape Town, W. Cape, SA. Saddlery manufacturer.
J.M. de Barros, Cape Town, W. Cape, SA. Orthotist and prosthetist.
THIS WEEK LAST YEAR!
Aflex fair moved to November
Wage negotiations: No settlements yet
Shipping times improve
Financial results
- Pepkor reports ‘strong retail growth’
- Fila, Acushnet parent Misto Holdings reports Q1 revenue gains despite tariffs
- Richemont posts robust performance for the year ended 31 March 2025
In case you missed it!: The May issue of S&V African Leather Magazine
READ IT HERE - S&V Weekly Newsletter Vol.11 No.20, May 19 2025
THIS WEEK FIVE YEARS AGO!!
Steinhoff 'will fight Tekkie Town founders' liquidation attempt', but they say it's necessary to reveal true extent of fraud
Botswana
- JB Sports: Better, but not as good as it should be
Namibia
- Agent: Slowly getting back to normal
Zimbabwe
- Safari Leathers: Tight, but positive signs
Financial
- TFG: Trading statement and update
- Pepkor 6-month results
Movements
- Doug Dare will retire as an executive director of Truworths International Ltd
READ IT HERE - S&V Weekly Newsletter Vol.7 No.20, May 17 2021
NEWSLETTER ARCHIVE
All the past S&V Weekly Newsletters from January 2016 onwards are available in the newsletter archive.
VIEW THE ARCHIVE - CLICK HERE
Contact us
News & Classifieds: Tony Dickson, +27 (0)31 209 7505, tony@svmag.co.za
Next newsletter: Monday 25 May, 2026. Ad and editorial deadline Friday 22 May 2026.
SAFLIA enquiries: Tel 0800SAFLIA * Email info@saflia.co.za * Website http://www.saflia.co.za
Our website www.svmag.co.za
|